U.S. Bank Mobile Banking

Screenshots
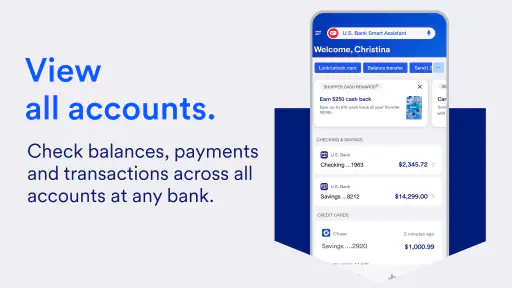
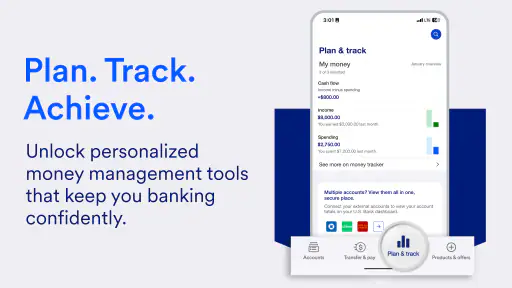
Details
- Rating
- 217.45K reviews
- Version
- 3.80.70
- Developer
- U.S. Bank Mobile
Analysis by Norviv
Managing a bank account from a phone sounds simple until everyday money tasks start competing for attention. A transfer before work, a card check at the checkout, a deposit after a weekend shift, and a quick look at spending can easily become a string of separate errands. After spending time with U.S. Bank Mobile Banking, I found that its main strength is not one flashy tool. It is the way it brings routine banking actions into one fairly consistent place.
This is a free finance app from U.S. Bank Mobile, rated for Everyone. It has been available since October 4, 2011, and the current version is 3.80.70 for devices running iOS 10 or later. Its 4.7 average from around 510,000 ratings and more than 10 million installs suggest that it has become a familiar option for a large group of customers. Those figures do not replace personal testing, though. Banking apps are judged by small details: how quickly I can find a transaction, whether a transfer is clear before I confirm it, and how much effort it takes to repeat a task.
How I use it for the everyday banking routine
My baseline workflow starts with the account overview rather than with a specific feature. I first check the available balance, then scan recent activity before moving money or paying anything. That order matters because a balance alone can be misleading when recent purchases, deposits, or scheduled payments have not yet become part of the mental picture. The app works best when I treat it as a daily control panel, not merely as a place to open when something goes wrong.
For a normal weekday scenario, imagine receiving a paycheck, buying groceries, and needing to confirm that a recurring payment will not cause a problem. I would open the app, review the relevant account activity, inspect the payment details, and then make the transfer or payment only after checking the destination and amount. This sounds cautious, but mobile banking rewards that habit. A few seconds spent reading the confirmation screen is more useful than rushing through a familiar sequence.
The account and transaction views are also useful for answering questions that otherwise lead to paper receipts or a desktop session. When I want to know whether a purchase has posted, I can search through recent activity instead of relying on memory. When I am reconciling a household budget, the transaction history gives me a practical starting point. I would still use a dedicated budgeting tool for deeper planning, but the bank app is the authoritative place to check what actually reached the account.
Depositing a check by phone is another situation where a repeatable process makes a difference. I would prepare the check, use a well-lit surface, capture both sides carefully, and keep the physical check aside until the deposit has been handled according to the bank’s instructions. The important insight is that the camera step is only part of the workflow. The confirmation and later account review are just as important, because they let me verify that the deposit appears as expected instead of assuming that a successful photo automatically means the money is ready to use.
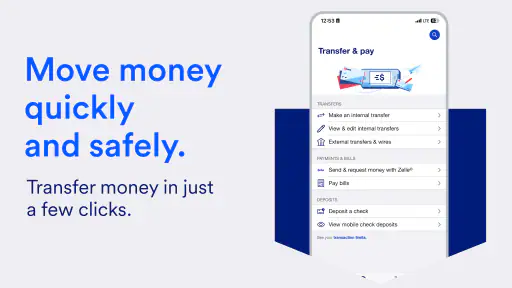
Transfers deserve the same discipline. I prefer to pause at the final review and confirm the source account, destination, amount, and timing. This is especially valuable when two accounts have similar names or when I am moving money to cover an upcoming payment. The app makes the action convenient, but convenience can also make an incorrect tap feel deceptively easy. I see the strongest benefit here as reduced friction, not permission to stop checking details.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
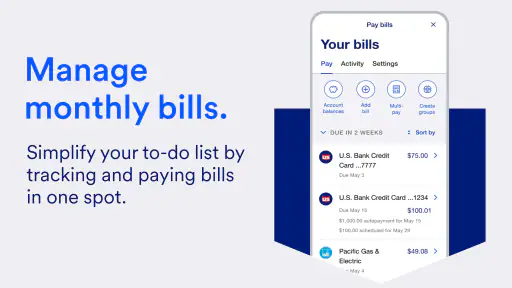
Payments are similarly straightforward when I already know what I want to do. I can use the app to manage a bill or review payment activity without opening a separate browser. For someone who pays a small set of regular bills, that centralization is genuinely helpful. For a complicated household arrangement with many payees, several account owners, or frequent changes, I would slow down and verify each entry rather than assuming that a previously used payment path is still the right one.
The settings I would check before relying on it
The first settings I would review are the security and sign-in choices. A finance app should fit the way I actually unlock my phone, while still requiring a deliberate step before sensitive actions. I would enable the strongest sign-in method supported by my device and make sure I know how to recover access if I replace the phone. This is not just a privacy preference: a banking routine becomes frustrating when the user discovers the recovery problem only while traveling or under time pressure.
Notifications deserve a careful review too. I would keep useful account alerts enabled, but I would avoid turning on every possible message without considering how often I want to be interrupted. A good alert setup should help me notice unusual activity, important account events, or a payment that needs attention. Too many low-value notifications create the opposite problem: the meaningful one gets buried among routine reminders.
I would also inspect how the app presents contact and account information before making a transfer. If the display allows me to distinguish accounts clearly, I would use names or descriptions that match my own household system. That small organizational step reduces the risk of selecting the wrong source account. Experienced users often focus on speed, but clear labels are a better form of speed because they reduce hesitation and correction.
Device maintenance is part of the settings conversation. I would keep the operating system supported by the app, install updates from the official app marketplace, and avoid using a banking session on a shared or unfamiliar device. U.S. Bank Mobile Banking is free, but the surrounding phone environment still matters. A strong banking app cannot compensate for a reused passcode, an unlocked phone left unattended, or a notification preview that exposes private information on a lock screen.
One setting I would not treat casually is automatic sign-in convenience. Fast access is pleasant when I am checking a balance at home, but I want the phone itself protected by a reliable lock method. I also prefer to close the session when I have finished a sensitive task, particularly if another person might use the device. These habits are more important than chasing a few saved seconds.
Shorter paths that make repeated tasks easier
After learning where the main actions live, I would build a simple sequence for each repeated job. For example, my “check and pay” pattern would be: open the app, review the account activity, open the payment area, verify the payee and amount, then read the final confirmation. My “move money” pattern would begin with the source account and end with a second look at the resulting activity. Repeating the same order reduces the chance that I will act on a balance without noticing a pending transaction.
Shortcuts are most useful when they remove searching, not when they encourage automatic tapping. I would keep the app easy to reach on the phone and use the quickest sign-in option that still feels secure. If the app offers a direct route to a familiar action on my device, I would use it only after learning what screen it opens and what information still needs checking. The best shortcut is one that gets me to the right review screen faster, not one that bypasses review altogether.
Another effective habit is separating observation from action. I might open the app in the morning only to review activity, then return later to make a transfer after I have confirmed the amount needed. That two-step approach is useful for irregular income or shared household finances, where the correct decision depends on more than the current balance. It also prevents a quick balance check from turning into an unnecessary transaction.
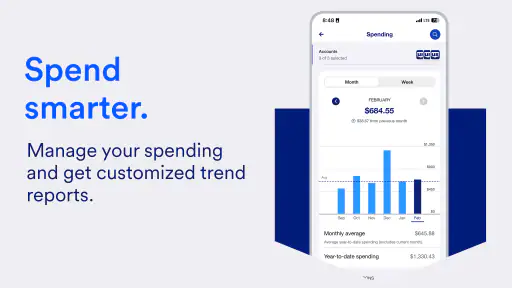
For spending reviews, I would choose a consistent day and scan the same account range each time. I would look for unfamiliar merchants, duplicate-looking entries, and subscriptions that I had forgotten about. This does not turn the app into a complete financial planner, but it creates a dependable review habit using the bank’s own transaction record. I find that more practical than opening a budgeting dashboard once and then abandoning it.
When traveling, I would prepare before leaving rather than waiting until a purchase is declined or a transfer becomes urgent. I would sign in once, confirm that I can reach the accounts I need, and make sure notifications are not being blocked by the phone’s travel or battery settings. I would also avoid relying on public Wi-Fi for sensitive banking actions when a safer connection is available. The app can make access easier, but preparation still determines whether that access is useful.
There is a trade-off between convenience and concentration. Mobile banking is excellent for a quick confirmation, but a phone screen is not always the best place to compare a large number of transactions or plan a complicated financial decision. For those jobs, I would use a larger screen or a dedicated spreadsheet alongside the app. The app remains the source I check for account reality; it does not need to be the only tool in my financial system.
Where its convenience reaches its limits
The biggest limitation is inherent to a bank-specific app: its value is highest when U.S. Bank is already where I keep my accounts. If my money is spread across several institutions, U.S. Bank Mobile Banking will not replace a broad financial dashboard that combines cards, loans, investments, and outside accounts in one view. I would choose a multi-account finance service for an overall household picture, while keeping this app for direct account actions and the most current bank records.
It is also not the ideal replacement for personal financial advice. The app can help me see balances, activity, and routine banking tasks, but it cannot decide whether I should refinance, change an investment strategy, or restructure a complicated budget. Those decisions need context that a transaction screen cannot provide. I appreciate the app more when I expect it to handle banking mechanics rather than solve every money problem.
Small-screen friction becomes more noticeable during detailed reviews. Reading several transactions, comparing dates, or checking a long payment history can feel slower than working on a desktop. I would not call that a serious flaw for quick tasks, but it is a reason to avoid doing complex reconciliation when I am distracted or in a hurry. A phone is convenient, not automatically comfortable for every financial task.
Security steps can also feel like friction, especially when I only want to check one detail. In my view, that is an acceptable trade-off for a finance app, but it still affects the experience. If someone wants instant access with almost no verification, this may feel less convenient than a general-purpose spending tracker. I would rather accept a deliberate sign-in than weaken the protection around financial information.
Compatibility should be considered before installing it. The app requires iOS 10 or later, so I would check the device software first rather than discovering the requirement during setup. The Everyone age rating makes it broadly suitable from a content perspective, but younger users still need an appropriate bank relationship and supervision around real-money decisions. An age label does not turn financial responsibility into a simple app feature.
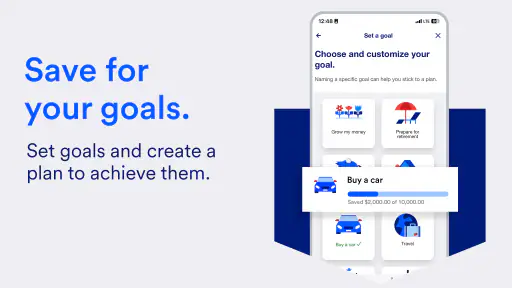
The app is not the right choice for someone who wants a completely institution-neutral experience, advanced investment analysis, or a visual budgeting system built around categories and long-term goals. It is also a poor fit for a person who refuses to review confirmations and prefers to automate every money movement without checking. Its convenience rewards attention; it does not remove the need for it.
What I would recommend after using it regularly
My overall impression is that U.S. Bank Mobile Banking succeeds through dependable routines. It gives U.S. Bank customers a practical way to check activity, manage common account tasks, handle transfers and payments, and keep banking close at hand. The free price removes an obvious barrier, and the large install base shows that the app is not a niche experiment. More importantly, I found that it becomes more useful after I organize my own habits around it.
The most valuable approach is to combine three things: clear account labels, carefully chosen alerts, and a repeatable confirmation process. That combination is more powerful than simply installing the app and hoping it will organize money automatically. I would review settings once, establish the shortcuts that fit my device, and then keep the same order for balances, payments, transfers, and deposits. The real advantage is controlled repetition, not blind speed.
I would recommend it to U.S. Bank customers who want direct mobile access and mostly handle everyday banking from a phone. It is especially suitable for people who value quick checks but are willing to pause before confirming a payment or transfer. It can also serve as a useful companion to a spreadsheet or separate budgeting tool, because the bank app provides the account-level record while the other tool handles planning.
I would steer someone toward a different option if they need one unified view of accounts at many banks, extensive investment research, or a richer budgeting workspace. I would also suggest a desktop session for complicated financial reviews rather than forcing every task onto a phone. Those are boundaries, not deal-breakers. In its intended role, the app is focused and practical.
With its current version, broad device support from iOS 10 onward, and a mature presence in mobile finance, U.S. Bank Mobile Banking feels like a sensible everyday tool rather than a novelty. I would install it when U.S. Bank is my primary institution, configure the security and notification choices before relying on it, and build a calm checking routine around it. For me, that is the difference between merely having a banking app and actually using it well.
Frequently Asked Questions
01What can I do with the U.S. Bank Mobile Banking app?
The U.S. Bank Mobile Banking app lets customers manage many everyday banking tasks from an Android or iPhone. After signing in, you can review account balances and transactions, transfer money, pay bills, deposit eligible checks, manage cards, find ATMs and branches, and send or receive certain payments. Available tools can vary depending on your account type, location, device, and U.S. Bank’s current service availability.
02Is U.S. Bank Mobile Banking safe to use?
The app includes security features designed to protect your banking information, such as encrypted connections, secure sign-in options, device recognition, alerts, and biometric authentication on compatible devices. However, no banking app eliminates every risk. Download it only from the official Google Play Store or Apple App Store, keep your operating system updated, avoid public Wi-Fi for sensitive activity, and never share passwords or one-time verification codes.
03Can I deposit checks using the U.S. Bank app?
Eligible customers can generally use the mobile check deposit feature by photographing the front and endorsed back of a check within the app. The images must be clear, and the check needs to meet U.S. Bank’s acceptance requirements. Deposit limits, availability of funds, processing times, and eligibility may differ by account and customer. Keep the original check safely until the deposit is confirmed and no longer subject to review.
04Does the app charge fees for mobile banking services?
Downloading and using the U.S. Bank Mobile Banking app is typically not charged as a separate app subscription, but normal account terms and service fees may still apply. For example, fees can depend on your checking account, overdraft activity, wire transfers, expedited services, or other transactions. Mobile data charges may also come from your carrier. Review the fee schedule associated with your account before using a paid service.
05What should I do if I cannot sign in or the app is not working?
First, check that your internet connection is stable and that you are using the latest version of the app from the official store. Restarting the app or device may resolve temporary problems, while resetting your password can help with forgotten credentials. Avoid repeatedly guessing login details, since access may be restricted. If the issue continues, contact U.S. Bank through an official support channel rather than relying on links from unofficial websites or messages.


